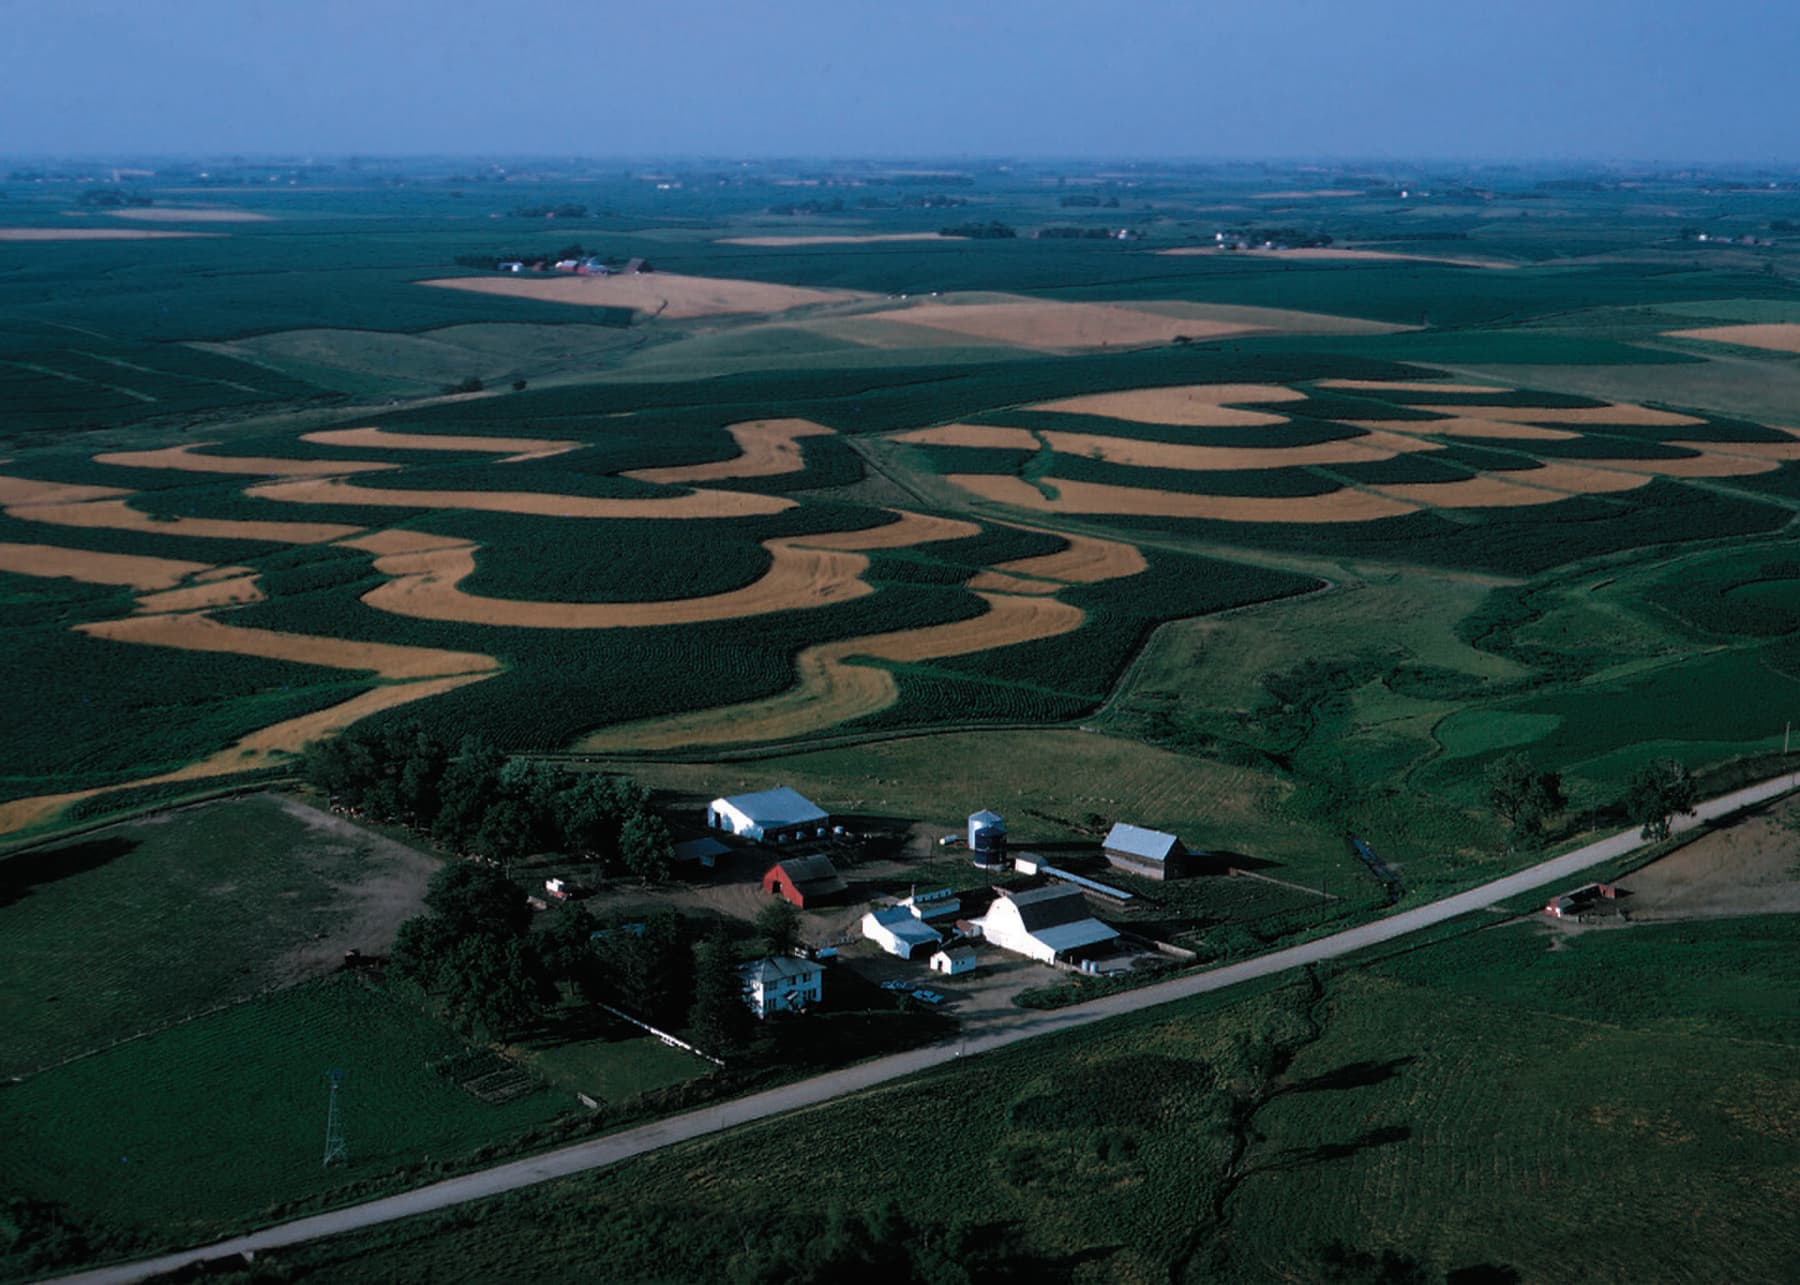
Aerial view of contour strip cropping curving around a farmstead in Iowa

The ecosystem dividend, field by field

Nature does $125 trillion of work a year. Almost none of it is paid for.

A farm produces more than yield: cleaner water, stored carbon, water held in the soil, habitat, a steadier harvest. On a tile-drained corn–soybean field in the Corn Belt, buyers would pay about $66 an acre a year for that work, at prices already paid somewhere in the US. TerraValue measures it, prices it, connects the people who benefit, and exists to get the money to the farmer.

$125 trillion is the value of all the world’s ecosystem services in 2011, in 2007 dollars (Costanza et al. 2014). $66 an acre is the working paper’s core bundle of cover crops, no-till and right-sized nitrogen. Both are estimates.

Model output · one surveyed field

York, Nebraska · Hord silt loam

TerraValue score

72/ 100+27 vs conventional

Net benefit vs conventional

$86per acre per year

Private
$8
Programs
$90
Costs
−$12

Six outcomes

Soil carbon+2.9 t CO₂e/ha83
Water quality4.9 kg N/ha leached94
Water quantity5 mm runoff74
Biodiversity$64/ac, not counted62
Yield resilience58% kept in a dry year67
Economics$86/ac net48

Reduced Till + Cover Crops. Reduced tillage with a grass cover crop, on the same soil, slope and climate as the conventional twin.

Run your own field →

USDA soil survey record and ERA5 climate 1991–2020 for one point. Estimates, not measurements.

Six outcomes, one field

What a field produces besides the crop.

Most tools price one thing, usually carbon. One management change moves all six at once, so TerraValue evaluates them together and shows the source behind every figure.

01

Soil carbon

Carbon gained or lost in the top 30 cm, and the nitrous oxide avoided when less nitrogen is applied.

Sequestration potential

0.5–1.5t CO₂/ha/yr

Global soil carbon stock
2,500 Gt C in top 2m
Voluntary carbon price
$5–50 per tonne CO₂e
US farmland carbon value
$8B+ potential/yr

Sources: IPCC, Lal 2004, Ecosystem Marketplace 2024

02

Water quality

Nitrate leaving the root zone, soil lost to erosion and phosphorus risk, against the conventional twin.

Des Moines nitrate plant

$16Kper day at full capacity

Nitrate cut, cereal rye cover
15–45 % decrease, 31% typical
Nutrient credit price
$2.50–13 per lb N, traded and auctioned
US clean water cost saved
$4B+ annual potential

Sources: Central Iowa Water Works, Iowa Nutrient Reduction Strategy, PENNVEST and Virginia nutrient trading, EPA

03

Water quantity

Rain captured, water pumped and what it costs, and how well the soil carries a crop through a dry spell.

Ag share of freshwater use

70% globally

Soil water holding gain, silt loam
+3,400 gal/acre per foot per 1% OM
Pivot irrigation, York NE
9.3 inches pumped per year (modeled)
Water trading market (2033)
$23B projected

Sources: Soil Health Exchange 2026 (after Minasny & McBratney 2018), FAO, TerraValue field model, Zion Market Research

04

Biodiversity

Habitat, pollinators, soil life and species, from how the field is tilled, covered, rotated, sprayed and edged.

Pollination service value

$235–577Bglobal/yr

Species richness, organic farms
+30 % vs conventional
CRP habitat payment
$145 per habitat acre/yr, average
Natural pest control, US
$4.5B per year, by insects

Sources: IPBES 2016, Tuck et al. 2014, USDA FSA CRP, Losey & Vaughan 2006

05

Yield resilience

Attainable yield for the climate, what water and nitrogen cost it, and how much is kept in a dry year.

Drought-year corn yield

+31% organic vs conventional, Rodale trial

Dry-year yield kept, York NE
46→58 % with reduced till + cover (modeled)
Soil health ROI timeline
3–5 years to break even
Cover-crop insurance discount
$5 per acre (Iowa, Illinois)

Sources: Rodale Institute Farming Systems Trial, TerraValue field model, Iowa Dept. of Agriculture

06

Farm economics

Private savings, program and market money, and costs, each kept apart, per acre and per field.

Nature finance needed by 2030

$571Bper year

Private share of 2023 flows
10 % of $220B
Land-sector credit market (2030)
$26.4B projected
Net benefit vs conventional, York NE
$86–163 per acre/yr (modeled)*

Sources: UNEP, The Business Research Company; *TerraValue field model, reduced till to regenerative
Atlas

Where the pressure is, county by county.

Before any field is measured, public data already shows where soil has lost its carbon, where the nitrogen and the water go on, what a dry year takes from the crop, and where a farm’s money goes. The Atlas draws it for every county, with the source and the date on each layer.

Soil organic carbon lost to land use, top 30 cmt C/ha, modeled

Land use of—

GainedLost

Source: Sanderman, Hengl & Fiske (2017), PNAS 114(36)

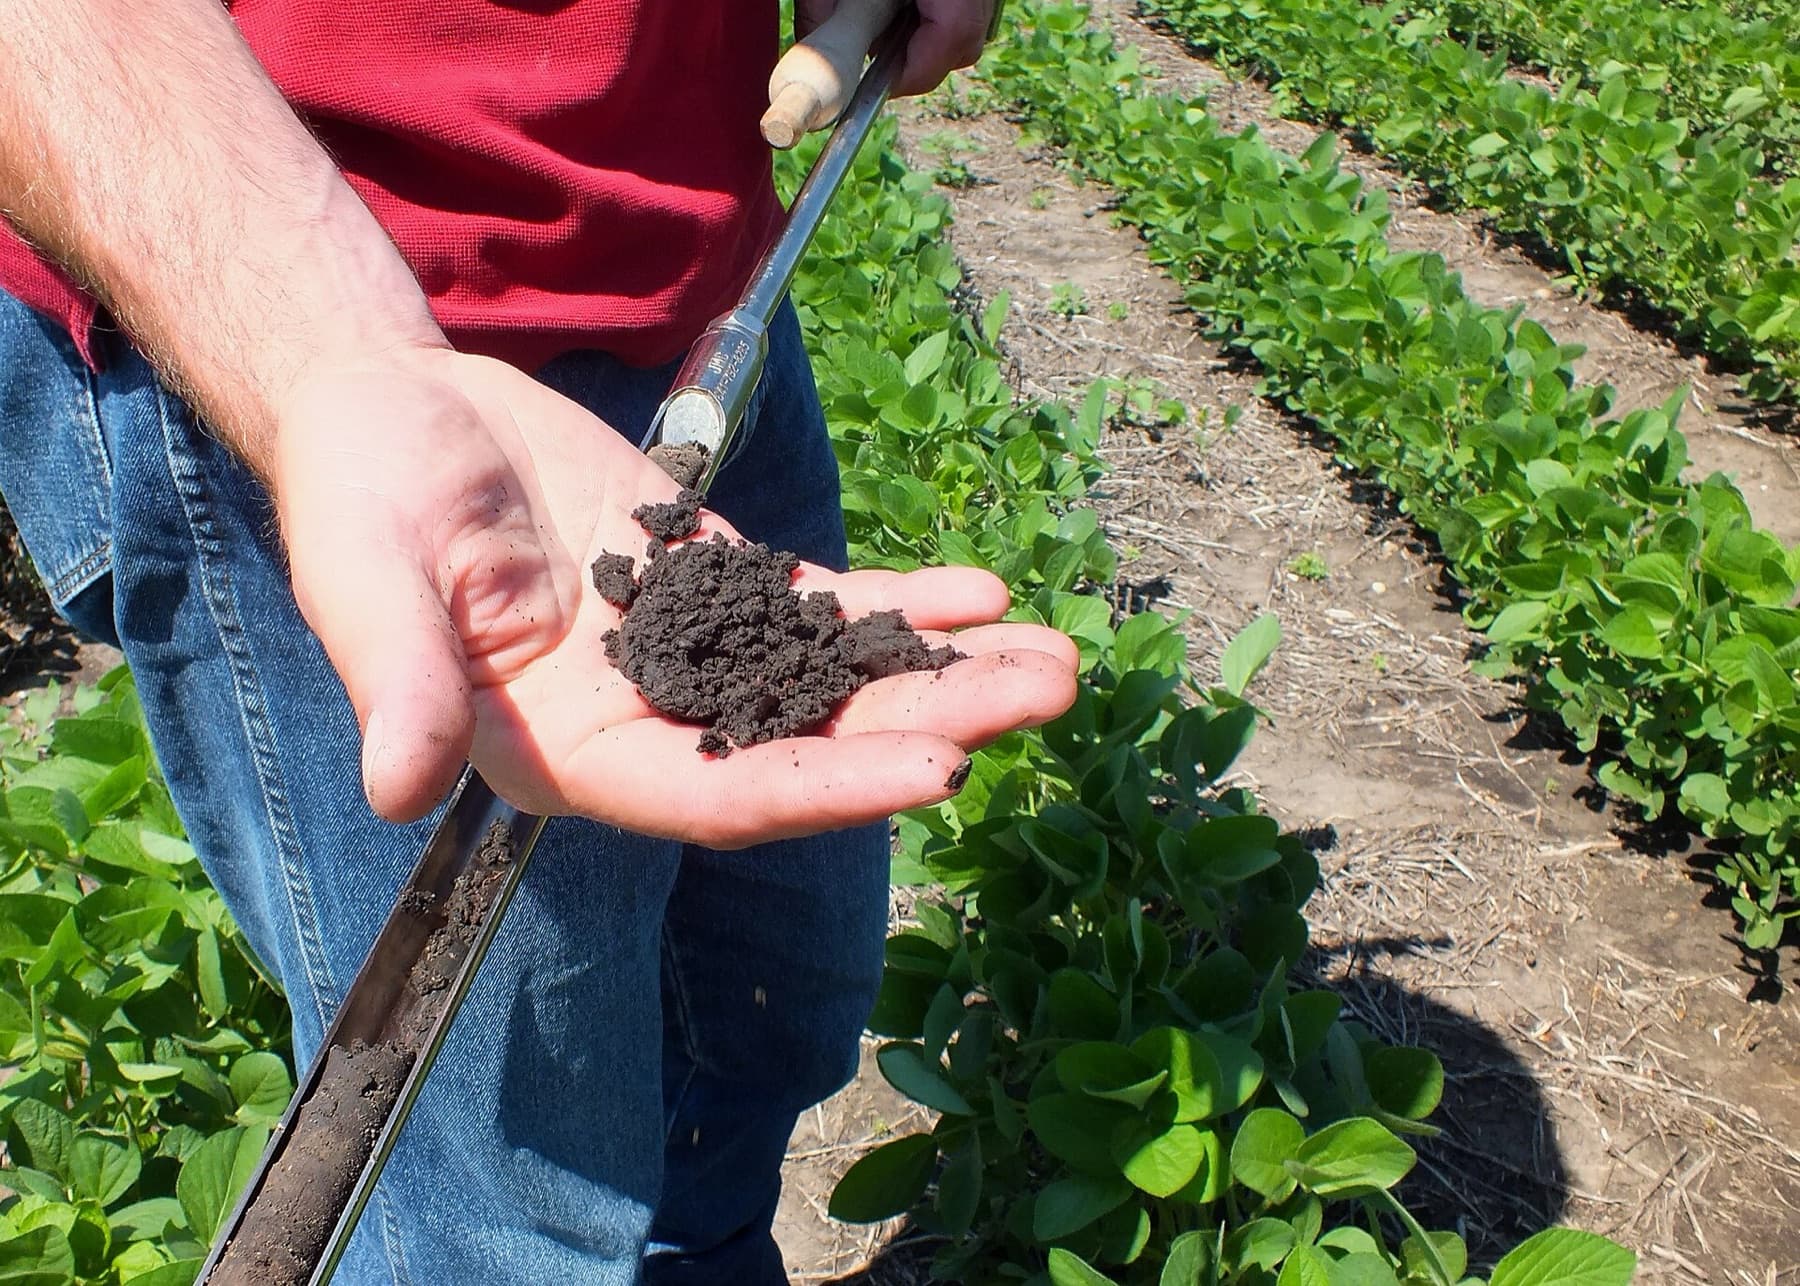
A hand holds dark soil from a probe in a no-till soybean field

Proof starts in the field

Records and invoices prove the practice. Soil samples and wells check the outcome.

How it works

Same field, two ways. The difference is what your practices are worth.

Every result is a comparison: the field as you farm it against the same soil, slope and climate under conventional tillage, no cover crop and synthetic nitrogen at the yield-goal rate.

1 · RESOLVEThe fieldUSDA SSURGO: soil series, horizons,drainage, slope (surveyed)ERA5 1991–2020 climate normalsManagement from the operator:tillage, cover, nitrogen, irrigation…provenance tagged on every input2 · COMPUTE THE STATEField agronomyMonthly soil-water balancewith irrigation and dry/wet yearsAnnual nitrogen budgetAttainable yield for the climatealso run for a conventional twin3 · MODELSix models, per hectarecarbon · water quality · water quantitybiodiversity · yield · economicst CO₂e · kg N leached · t soilmm pumped · bu/ac · $/haevery figure vs the conventional twin4 · PRICE AND SCALEOne numberprivate moneyprogram and market moneycosts× field areawith its range and its sources
  1. 01

    Resolve the field

    A pin or a drawn boundary is looked up in the USDA soil survey and thirty years of climate: texture, organic matter, drainage, slope, rain, heat.

    Output Soil and climate, with their source

  2. 02

    Add how it is farmed

    Ten answers from the farmer: crop, tillage, cover crop, nitrogen rate, rotation, irrigation, tiles, years in practice.

    Output A management record

  3. 03

    Run it two ways

    A monthly water balance, a nitrogen budget and six outcome models run on the field as farmed, and again on the same field farmed conventionally.

    Output Outcomes against a conventional twin

  4. 04

    Price it and keep the books

    Each difference is priced at what a named buyer already pays. Private savings, program money and costs are never mixed.

    Output Dollars per acre, by who pays

Three kinds of money

Your money, other people’s money, and what it costs.

Private savings land on the operating budget whether or not anyone pays. Program and market money is contingent on a buyer. A lender treats them differently, so the model never mixes them.

Three kinds of money on one field

York, Nebraska · USD per acre per year, against conventional management on the same field

Field

  • Private, on-farm
  • Programs and markets (contingent)
  • Costs
  • Net

Reduced till + cover: net

$86/ac

$13,727 a year on 160 acres

of which private, underwritable today

$8/ac

fuel, fertilizer, chemicals and the soil that stays

programs that need a counterparty

$90/ac

biodiversity shown but not counted: $64/ac

Model output for named fields. The conventional program nets to a few dollars by construction, because every line is a difference from it.

Working Paper 01

The ecosystem dividend.

A recurring payment to the steward of an acre for the clean water, carbon and habitat it produces, funded by the people who benefit. The working paper sets out the mechanism, the prices, the evidence tiers, and what one Nebraska field actually produces.

Core bundle: cover crops, no-till and right-sized nitrogen. Base prices. Sampled evidence tier, where 80% of a modeled outcome is paid.

$0

an acre a year that buyers would pay for the core bundle, at prices already paid somewhere in the US

$0

reaches the steward after the evidence discount, a risk reserve and verification

0%

of that value is water. The anchor buyer is whoever owns the nitrate problem, not the carbon market

$0

more an acre reaches the steward when the outcome is measured in the field instead of modeled. Evidence is what a buyer pays for

Why now

The value is counted in trillions. The payments are not.

Three published figures frame the gap: what nature’s work is worth, what it costs when a field loses nitrogen, and how little private money pays for either. Each is an estimate with a wide range, and each links to its source.

$125T/yr

estimated value of the world’s ecosystem services in 2011

In 2007 dollars, across every biome, against a world economy of about $75 trillion that year. The same study put the yearly loss from land-use change at $4.3 to $20.2 trillion.

Costanza et al. 2014, Global Environmental Change

$210B/yr

health and environmental damage from nitrogen released in the United States, early 2000s

The range is $81 to $441 billion a year, in 2008 dollars. This is the bill a pound of nitrate kept in the field is priced against.

Sobota et al. 2015, Environmental Research Letters

$571B/yr

nature-based solutions investment needed by 2030

UNEP says private finance contributed only $23 billion. The money and the buyers exist. What is missing is a way to measure an outcome, price it and pay the person who produced it.

UNEP State of Finance for Nature 2026

Agriculture is a $4.5 trillion system before nature is priced.

Global agriculture, forestry, and fishing value added has grown roughly fourfold since 2000, reaching $4.55T in 2024.

The economic base is already enormous. What is missing is a measurement layer for the ecosystem value produced alongside it.

US$ trillions

Build this with us

Tell us what your side of the market needs.

Farmers, nutrient and water-quality traders, crop insurers, lenders, food and fuel companies, and sustainability teams each pay for a different piece of what a field produces. Tell us what you would need to see before you could pay for an outcome, price a risk on it, or be paid for one.

01

Name the gap

Tell us where today's programs, markets and tools fall short for you.

02

Define what useful means

Share the decision, evidence, or value you need a better tool to unlock.

03

Help shape TerraValue

Your perspective will inform product priorities, and you'll join the early-access list.

What TerraValue is building toward

One transparent evidence system that connects field decisions to soil, water, biodiversity, resilience, and financial value—shaped by the gaps you share.

1 · Your perspective
2 · Where today's approach falls short

Choose any that reflect your experience.

3 · Stay involved

We use your response to shape TerraValue and contact you about relevant access.