Working Paper 01 · The proposition
The Ecosystem
Dividend
What if the people who benefit from cleaner water, carbon storage and habitat helped pay the farmers who produce them?
TerraValue / 30 September 2026 / 18 min read
Updated 22 October 2026
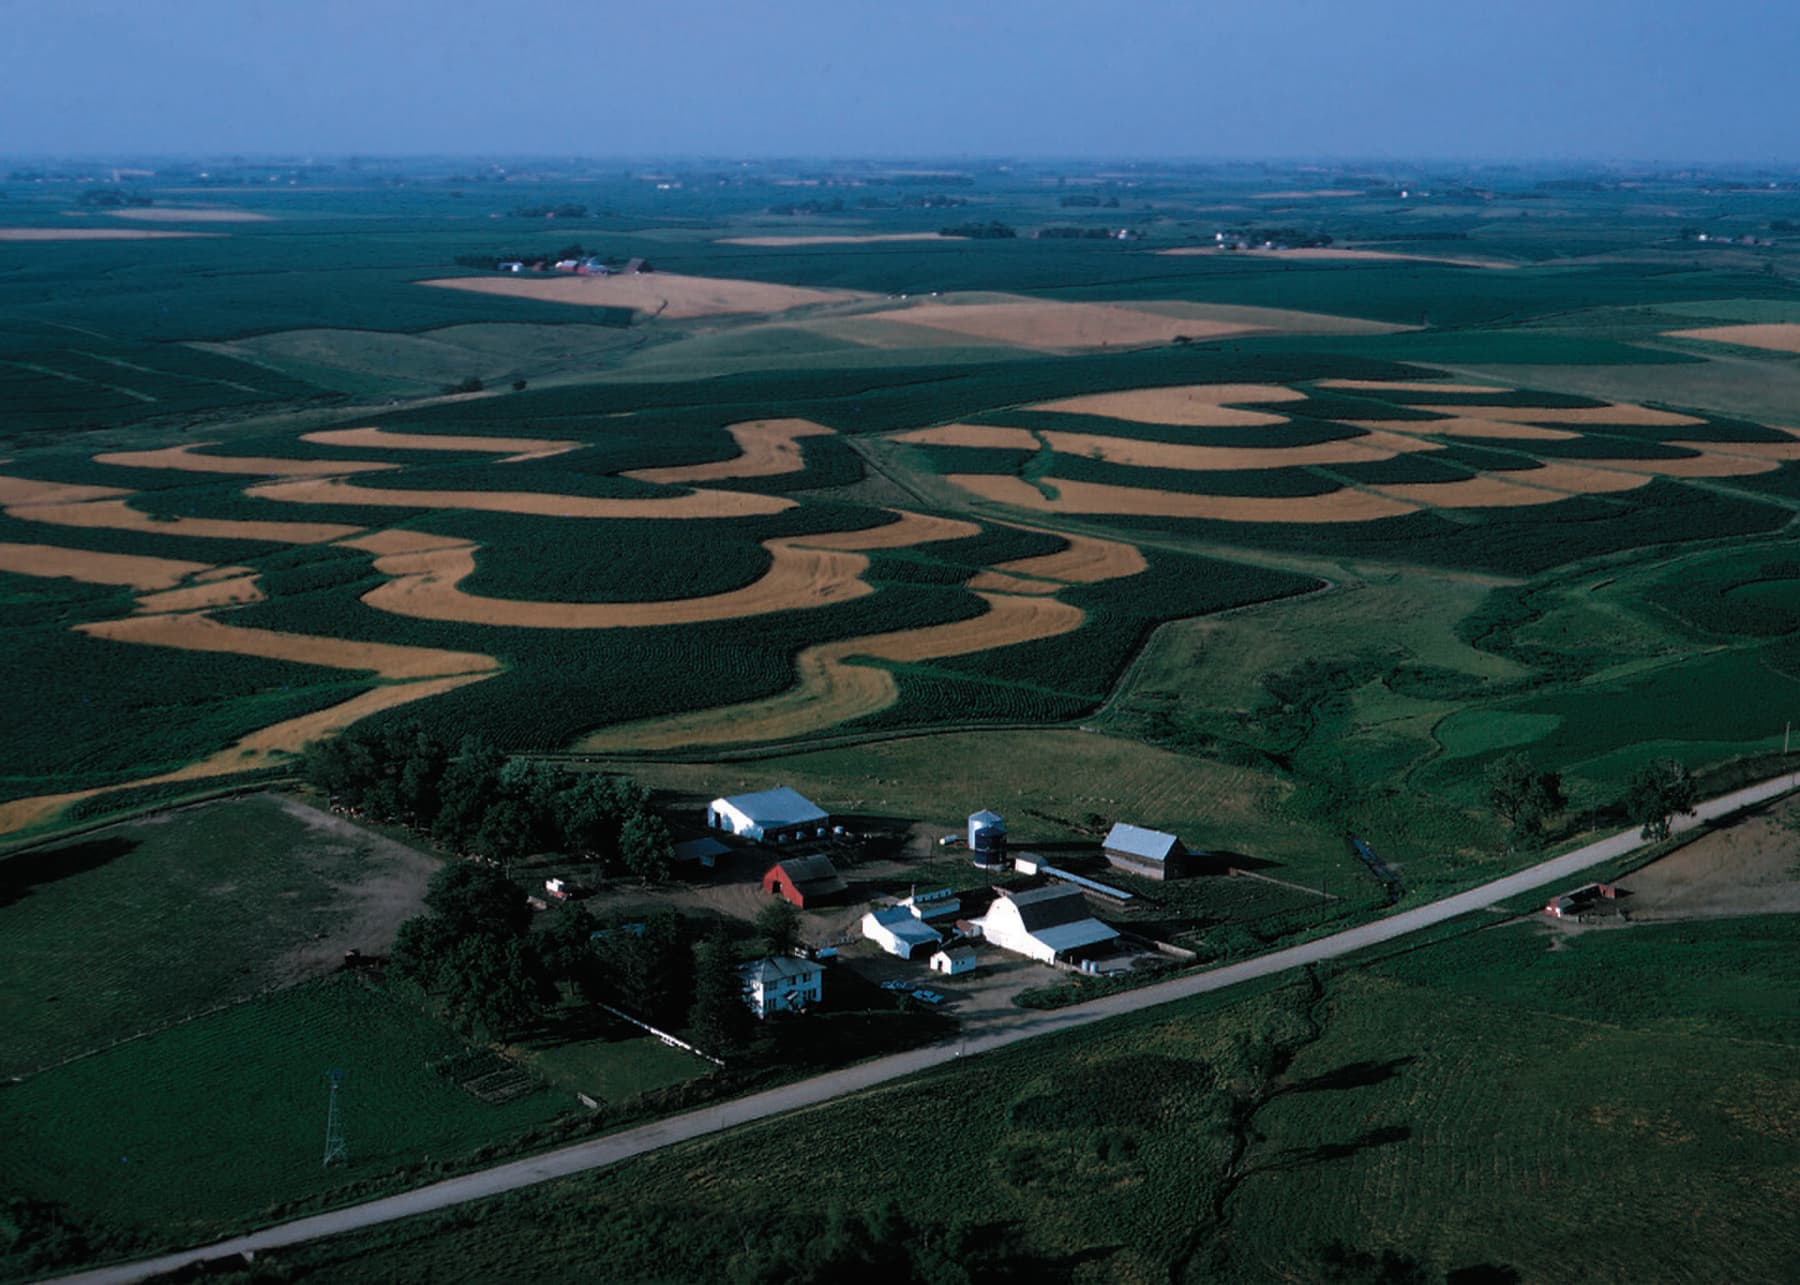
What if every acre paid its steward a dividend?
Abstract
A farm can produce clean water, climate benefits and habitat while its steward carries the cost of the work. We propose an ecosystem dividend: a recurring payment funded by the institutions that can use and accept those outcomes. The question is whether the physical benefit, the evidence and the buyer’s budget can meet on the same acre.
This paper makes the proposition inspectable. A societal-value benchmark illustrates the gap between shared benefit and farm revenue. A public scenario model then prices a bundle of cover crops, no-till, nitrogen right-sizing: the base case produces a proposed payment of $42 per acre per year after its confidence rule, reserve and administration allowance. Field examples in Nebraska show where physical estimates come from, while the farm calculator and adoption scenarios let readers change the assumptions. These are modeled possibilities for a pilot to test; accepted evidence, eligible funding and signed agreements are still required.
- estimated public value of a regenerative acre, per year (benefit transfer, not a price)
$477
estimated public value of a regenerative acre, per year (benefit transfer, not a price)
- reference carbon revenue as a share of the societal-value benchmark
6%
reference carbon revenue as a share of the societal-value benchmark
- proposed steward payment per acre per year, under the base scenario
$42
proposed steward payment per acre per year, under the base scenario
- modeled stewardship acres in 2040 vs. the modeled status quo
4.3×
modeled stewardship acres in 2040 vs. the modeled status quo
The public dividend model is published in full. The field examples show outputs; proprietary field-model methods remain in the confidential paper.
1The value gap
Shared benefit and farm revenue are different numbers.
Using TerraValue’s benchmark composite, an acre under regenerative management produces roughly $477 a year in societal value. Its separate carbon-revenue benchmark is about $30an acre. The comparison illustrates how much shared benefit can sit outside a farm’s direct revenue; it does not measure the payments received by every farmer or account for every conservation program.
These are societal values, what the outcomes are worth to someone, not prices anyone has agreed to pay. The dividend below uses separate price references and carbon-price outlook assumptions. Its proposed payment is much smaller than the societal-value benchmark and still requires a buyer with a relevant budget.
Explore the value gap
A landscape creates several kinds of value.
Select a service to explore what its value means and what would still be needed to turn it into a payment. US$ per acre per year, using the paper’s benchmark composite.
Water
$142/acre/yr · societal benchmark
Cleaner water can benefit households, utilities and ecosystems. A useful agreement identifies the water source, the delivered reduction and the evidence a buyer accepts.
A societal water benefit is not automatically a utility saving or a tradable nutrient credit.
Both rows are benchmark estimates. This comparison is not a measured payment rate across all farms or a forecast of available buyer funding.
2Why adoption stalls
Three censuses, one plateau.
Cover crops are the best-measured stewardship practice in the US. A logistic curve through the last three Censuses of Agriculture levels off at 19.3 million acres, 5.1% of cropland. Adoption grew 50% from 2012 to 2017, then 17% to 2022 (Figure 2). That fit suggests slowing adoption; three observations cannot establish a permanent ceiling.
US cover crop acres, and the curve they imply
Million acres
- USDA Census of Agriculture (reported)
- Logistic fit — dashed where extrapolated
Three observations give context to that slowdown.
- 31% of EQIP applications were funded, FY2017–22 (avg. 120,606 a year). farmdoc daily, 2023
- 27.3% vs 4.7% cover-crop share of cropland: Maryland, which pays per acre every season, vs. the US (2022 Census). USDA NASS, 2022 Census
- $6.34/t average voluntary carbon credit price across all credit types, 2024. Ecosystem Marketplace, 2025
Cost-share contracts usually support specified practices for a defined term. Carbon programs focus on a particular outcome and apply their own additionality rules. Table 1 compares these broad approaches with the proposed dividend.
Table 1. How the ecosystem dividend differs from cost-share contracts and carbon credits.
| Dimension | Cost-share contract | Carbon credits | Ecosystem dividend |
|---|---|---|---|
| Pays for | Installing a practice | Tonnes of CO₂e | A basket of measured outcomes |
| Paid | For the life of a contract | Per verified issuance, after year 1 | Every year the outcomes persist |
| Funded by | Taxpayers — when funded (31% of EQIP applications were, FY17–22) | Carbon buyers | Each beneficiary, per unit of what it uses |
| Early adopters | Eligibility varies by program | Eligibility and additionality depend on the protocol | Proposed stewardship eligibility against a regional benchmark |
| Share of an acre’s value addressed | One practice at a time | ~13% (climate only) | Carbon, water, habitat, resilience |
| Evidence | Practice was installed | Protocol sampling, pass or fail | Tiered — better evidence earns a larger share |
3How it works
Beneficiaries pay per unit. Stewards receive one dividend.
A dividend is what an owner receives for holding a productive asset. Farmland’s natural capital is that asset; its outcomes are the return. The mechanism connects the people who use those outcomes to the people who produce them, through a ledger both can audit (Figure 3).
01
Those who benefit pay
Water utilities · per lb of nitrate kept out
Des Moines runs a nitrate-removal plant at up to $16,000 a day.
Food & ag companies · per t CO₂e in their supply shed
Scope 3 targets sit on the same acres they source from.
Insurers & lenders · risk evidence or financing
State programs offer cover-crop premium discounts. Private risk pricing still needs its own evidence and agreement.
Public programmes · eligible stewardship support
CRP, EQIP and eco-schemes fund specified conservation activities under their own rules.
02
Program agreements
- Buyers agree units, evidence, prices and dates
- Compatible funds follow their permitted routes
- A 10% reserve is assumed in this model
03
Outcome ledger
- Outcomes assessed against an agreed baseline
- Proposed confidence rule sets the share paid (60–95%)
- Evidence, rights and permitted claims recorded
04
Stewards
- A contracted recurring stewardship payment
- Early-adopter eligibility agreed in advance
- Owner–tenant rights set before work begins
Beneficiaries agree eligible purchases and funding routes; outcomes and claims are recorded with their evidence; stewards receive contracted recurring payments.
The design follows four rules.
- Pay for outcomes, not practices. The unit is a pound of nitrate kept out of the river or a tonne of carbon stored — whatever practice produced it.
- Benchmark against the region, not your own past. A farmer who adopted cover crops a decade ago is still producing clean water. Paying against a regional baseline stops punishing the early movers.
- Pay more for better evidence. Nothing is paid until the practice itself is verified, from field records, input invoices or imagery. A confidence factor κ then pays 60% of a modeled outcome, 80% once sampled, 95% once measured. Proof of practice opens the door; better evidence of the outcome earns more.
- Sell each outcome once. Reductions from stacked practices compound instead of adding, and a ledger assigns every unit to exactly one buyer.
4The model
One line of arithmetic.
For each service, multiply the verified quantity by the price its beneficiary pays. Then pay the steward the share that the evidence supports, after a risk reserve and the cost of measurement:
Explore the evidence rule
Same acre. Same prices. Different evidence.
Change the evidence tier to see how the proposed payment rule works. The practice bundle, physical estimate and base price scenario stay fixed.
Models calibrated with stratified soil and water samples.
- Modeled reference value
- $65.98/acre/yr
- After the confidence rule
- $52.78/acre/yr
- Proposed steward dividend
- $42.22/acre/yr
How the reference value is allocated by the model
- Outside the paid confidence share
- $13.19
- Risk reserve
- $5.28
- Evidence & administration
- $5.28
- Steward dividend
- $42.22
$65.98 × 80% × (1 − 10% reserve − 10% administration) = $42.22 per acre per year.
The confidence shares, reserve and administration allowance are design assumptions. They are not statistical confidence intervals or quoted service costs. The unpaid confidence share is excluded from this payment calculation; it is not cash already collected from a buyer. Measurement still needs an accepted method and a funded agreement.
Change the practices and prices in the full farm calculator ↓- Qₛ
- verified quantity of service s per acre: t CO₂e, lb nitrate-N, habitat acres, enrolled acres;
- Pₛ
- the scenario price per unit, drawn from program references and carbon-price outlooks; a real purchase requires an agreed price;
- κ
- the confidence factor, applied only once the practice itself is verified: 60% modeled, 80% modeled + sampled, 95% measured;
- r
- the risk reserve, 10%, held against shortfall and released if outcomes hold;
- f
- a measurement, verification and administration allowance of 10% in this scenario.
Table 2 works the arithmetic for the core bundle of cover crops, no-till, nitrogen right-sizing on one acre of a tile-drained corn–soybean field, US Corn Belt, at base prices with sampled evidence, in 2026.
Table 2. Worked example: the core bundle on one acre. The reference value uses the scenario’s quantities and prices; the proposed steward dividend is 64% of it after κ, r and f. These figures are not contracted buyer funds.
| Service | Q per acre | P | Reference value | Proposed dividend |
|---|---|---|---|---|
| Carbon | 0.68 t CO₂e | $20 | $13.60 | $8.70 |
| Clean water | 9.47 lb nitrate-N | $5.00 | $47.38 | $30.32 |
| Habitat | 0.00 habitat acres | $145 | $0.00 | $0.00 |
| Resilience | 1.00 enrolled acres | $5.00 | $5.00 | $3.20 |
| Total | × 64% paid | $65.98 | $42.22 |
Clean water carries the dividend, 72% of it. The bundle removes 38% of the field’s 25 lb baseline nitrate loss; reductions compound rather than add.
This design also includes early adopters. Under its proposed stewardship rule, the same acre farmed this way for years receives $38 an acre. Actual program eligibility and carbon additionality depend on the applicable rules and contract.
5One field in Nebraska
Where Q comes from: a field priced from the soil survey up.
The arithmetic above needs a credible quantity per acre and accepted evidence. The field examples start with estimates from a field model that starts with a pin on a map, pulls the USDA soil survey record and thirty years of climate for that point, takes the operator’s management, and computes what the field does: how much water it uses and pumps, how much nitrate leaves the root zone, how much soil stays, what it yields, and what each of those is worth against a conventional version of the same field (Figure 4).
The interactive charts in this section use published model outputs for two named Nebraska fields: a loess field near York and a Sandhills field on Valentine fine sand. They are outputs, not the method. The method, with its parameters, its calibration record and its known gaps, is in the confidential working paper described at the end of the section.
Trace the estimate
From a field boundary to a decision.
Select a step to see what goes in, what comes out and what still needs to be established.
Start with a place and a record of its management.
- What goes in
- A field boundary, its location and the operator’s management records.
- What comes out
- Soil survey attributes from USDA SSURGO and climate normals from ERA5, with a source attached to each input.
The boundary of this step: A survey record describes a mapped soil unit. A sample is still needed to establish conditions at a particular point.
For the utility row of the mechanism, the field model produces the one number a water buyer needs: kilograms of nitrate per hectare per year that leave the root zone, for this field under this management, against the same field farmed conventionally. Nebraska already has an instrument that pays for the practice side of that. The Nitrogen Reduction Incentive Act pays producers in wellhead protection areas for a documented cut in fertilizer, and the documentation must be an NRD-approved method. A field budget can help assemble that evidence; the NRD must still approve the method.
What the model does not yet do is as important as what it does. It computes what leaves a field; it does not yet route that load to a named well through the aquifer, with the years of lag that implies, and it does not yet model the canal and furrow irrigation that dominates the North Platte valley. Both are on the roadmap in section 11. A buyer should expect the field figure, not the well figure, until they are.
Figures 5 to 7 are interactive; each has a data table underneath.
The water year on a named field
York, Nebraska · Hord silt loam, 0 to 1 percent slopes, warm · 775 mm rain, 1,194 mm reference ET
Field
Management
- Precipitation
- Irrigation applied
- Crop demand (ETc)
- Actual ET (ETa)
mm per month
Water in
1012 mm
775 rain + 237 irrigation (9.3 in)
Actual evapotranspiration
870 mm
100% of what the crop wanted in season
Deep percolation
91 mm
past the roots: recharge, or what carries nitrate
Pumping energy
$231/ha
207 bu/ac of 235 attainable
Center-pivot corn, strip-till. Model output; soil from the USDA survey, climate from ERA5 normals.
Nitrogen rate, as the field model sees it
Irrigated corn on York, Nebraska · drag the rate; the three panels move together
Field
Corn yield, bu/ac
Net benefit vs conventional, $/ha/yr
Nitrate leached past the roots, kg N/ha/yr
Yield at 160 kg N
197 bu/ac
217 at 280 kg; 85 with none
Net benefit at 160 kg N
$147/ha
best $147/ha near 160 kg N; conventional program 188 kg
Leached at 160 kg N
7.1 kg N/ha
26.1 kg at 280 kg N
Dotted line: the rate that maximises net benefit on this field. Fertilizer saved below it is charged for the yield it gives up; above it, extra bushels cost more than they return and leaching keeps rising.
Three kinds of money on one field
York, Nebraska · USD per acre per year, against conventional management on the same field
Field
- Private, on-farm
- Programs and markets (contingent)
- Costs
- Net
Reduced till + cover: net
$86/ac
$13,727 a year on 160 acres
of which private, underwritable today
$8/ac
fuel, fertilizer, chemicals and the soil that stays
programs that need a counterparty
$90/ac
biodiversity shown but not counted: $64/ac
Model output for named fields. The conventional program nets to a few dollars by construction, because every line is a difference from it.
On the York field, reduced tillage with a grass cover crop nets about $86 an acre against conventional management. $8 of that is private money the operator keeps whether or not anyone pays for it; $90 is programme and market money that needs a counterparty. That second figure is larger than the dividend computed in section 4 ($42 an acre) mainly because it includes EQIP and CRP payments, which the dividend leaves out; the outcome-priced lines alone, carbon and water, come to $32 an acre, priced at the same nitrate price as section 4. The field figure is also specific: this soil, this slope, this climate, this programme, against a conventional twin, with the irrigated corn next door drawing 237 mm from the aquifer and leaching 12.9 kg of nitrate per hectare.
A lender reads the three colours differently. Underwrite the green. Haircut the teal by the probability that each counterparty signs, and by its term. Treat the brown as certain. The gap between the private figure and the full figure is the dividend question, and it is now a number on a named field rather than a national average. Figure 8 shows who could close that gap.
6Run it on a farm
Does it pay to switch?
Figure 9 lets you choose the practices, the price scenario and how well the outcomes are evidenced. The cash-flow chart includes what the switch really costs: seed and passes, input savings, and the yield drag farmers report in the first years. At base prices, only the dividend ends ten years ahead ($140 an acre); cost-share ends at −$42 once its contract lapses, carbon credits alone at −$209.
Practices on the field
Price scenario
Evidence tier
Dividend per acre, year 1
$42
10-yr average $42
Per farm, year 1
$19.5K
463 acres
Buyers pay per acre
$66
64% reaches the steward
Dividend breaks even
Year 3
Cost-share contract: not in 10 yrs · Carbon credits only: not in 10 yrs
Per acre per year this bundle stores 0.68 t CO₂e, keeps 9.5 lb nitrate-N (38% of the baseline loss) out of the water.
From what buyers pay to what the steward receives
US$ per acre, year 1
Cumulative net position per acre, by how the farmer is paid
US$ per acre · practice costs, input savings, and transition yield drag included
- Ecosystem dividend
- Carbon credits only
- Cost-share contract
- No payment
Year 1 = 2026. Cost-share pays for 3 years. Carbon credits start after the first verification and exclude early adopters. Prices follow the “Base” scenario; modeled + sampled evidence pays 80% of the modeled outcome.
7If it scaled
84 million acres by 2040.
The projection combines the three-point census fit with Maryland’s observed cover-crop share and its reference $50/acre recurring payment. This is a calibration assumption rather than a causal estimate. An exponential response curve (scale λ ≈ $96/acre) maps any recurring payment to an adoption ceiling, capped at 60% of cropland.
Under the base scenario, stewards would receive $3.5B a year by 2040, about 1.7× EQIP’s annual budget, while beneficiaries pay $5.5B for 57 Mt CO₂e and 794M lb of nitrate-N kept out of water each year (Figure 10).
Price scenario
Evidence tier
Enrolled acres, 2040
84M
22% of cropland · 4.3× status quo
Paid to stewards, 2040
$3.5B/yr
Buyers pay $5.5B · $42/acre
Carbon, 2040
57 Mt
CO₂e stored or avoided per year
Nitrate-N kept out of water, 2040
794M lb
per year, on enrolled acres
Acres enrolled in the core bundle
Million acres · 2026 starts at the census-fitted curve
- Ecosystem dividend
- Carbon credits only
- Status quo
Money flowing to stewards each year
US$ billions per year
- Buyers pay (dividend)
- Stewards receive (dividend)
- Carbon credits only
Acres diffuse at the rate fitted to the 2012–2022 census and rise toward a ceiling set by each policy’s recurring per-acre payment, calibrated so that $0 reproduces today’s plateau and $50 reproduces Maryland’s 27.3% share. Buyer demand at scenario prices is assumed, not modeled.
8What moves the number
Two unsettled prices, and one lever we control.
The nitrate price and the carbon price swing the dividend most: the two prices markets have not settled. The largest lever a programme controls is evidence. Moving from modeled to measured outcomes adds $18 an acre on the core bundle under the proposed confidence rule. Figure 11 expands the comparison to all four practices.
What moves the dividend: each assumption swung low → high, all others at base
Net $/acre, 2030, all four practices, modeled + sampled · base $58
- Price of a pound of nitrate-N$40$114Price of a pound of nitrate-N: $2.50/lb gives $40; $13/lb gives $114.
- Carbon price$53$121Carbon price: $10/t gives $53; $146/t gives $121.
- Practice nitrate reduction$41$74Practice nitrate reduction: Low gives $41; High gives $74.
- Baseline nitrate loss$44$73Baseline nitrate loss: 15 lb gives $44; 36 lb gives $73.
- Evidence tier (confidence paid)$43$69Evidence tier (confidence paid): 60% gives $43; 95% gives $69.
- MRV fee + risk reserve$51$65MRV fee + risk reserve: 30% gives $51; 10% gives $65.
- Soil carbon accrual rate$53$62Soil carbon accrual rate: Low gives $53; High gives $62.
- Habitat price$53$61Habitat price: $72/ac gives $53; $191/ac gives $61.
- Insurer resilience discount$55$61Insurer resilience discount: $0/ac gives $55; $10/ac gives $61.
Price of a pound of nitrate-N: $2.50/lb → $40/acre; $13/lb → $114/acre. Swing $74.
- Below the base case
- Above the base case
Bundle: cover crops, no-till, nitrogen right-sizing, prairie strips. Hover or tab through a row for its input values.
9Precedents
Beneficiary-pays is not new. Stacking it is.
Each piece of the dividend already exists somewhere. What does not yet exist is one mechanism that pays for all of them, on the same acre, from everyone who benefits.
9.1 Catskill/Delaware watershed
New York City, USA · since 1997 · paid by city water ratepayers
Instead of building a plant that would also cost roughly $1M a day to run, the city pays upstream landowners to keep water clean at the source — about $100M a year since 1997. ~$2.5B vs $8–10B: spent protecting farms and forest upstream vs. the filtration plant it avoided.
Beneficiaries pay when they can compare stewardship against an avoided cost. National Academies, 2020
9.2 Payments for Environmental Services
Costa Rica · since 1997 · paid by 3.5% of national fuel-tax revenue
A dedicated, recurring revenue stream pays landowners roughly $64 per hectare a year to keep forest standing. More than a million hectares have been enrolled. 21% → 52%: national forest cover, 1987 to 2015.
A permanent funding stream outlasts project-by-project money. CBD case study
9.3 Vittel catchment
Vosges, France · since 1993 · paid by nestlé Waters (the bottler)
The bottler paid 26 farms about €200/ha a year through the transition, plus equipment, under 18- to 30-year contracts — €24.25M over 1993–2000. 92%: of the sub-basin under protective farming by 2004.
One beneficiary can underwrite a whole catchment when the outcome it needs is specific. IIED, Perrot-Maître 2006
9.4 Cover crop premium discount
Iowa & Illinois, USA · since 2017 · paid by state programmes via crop insurance
A $5/acre crop-insurance discount for cover-cropped acres. Illinois’ first 50,000-acre round filled in seven days. 1.2M+ acres: enrolled in Iowa’s $5/acre discount to date.
A state-funded premium discount can encourage adoption; it does not by itself demonstrate an insurer-funded resilience price. Iowa Dept. of Agriculture
9.5 Cover crop grant
Maryland, USA · since 1990s · paid by state Chesapeake Bay restoration funds
A per-acre grant paid every season — $50 base in 2023–24, up to $105 with add-ons — on nearly 450,000 acres. 27.3% vs 4.7%: of cropland in cover crops, Maryland vs. the US (2022 Census).
Recurring support accompanies high cover-crop adoption here; the comparison alone does not isolate the effect of payment. Maryland Dept. of Agriculture
9.6 CAP eco-schemes
European Union · since 2023 · paid by eU agricultural budget
At least a quarter of direct farm payments must now go to schemes that pay for environmental and climate practices. €44.7B: ring-fenced for 158 eco-schemes over 2023–2027.
Public farm budgets are already moving from income support toward paying for outcomes. European Commission
10What could break it
The failure modes, and the design answer to each.
Table 3. Risks to the ecosystem dividend and the design response to each.
| Risk | Why it matters | Design response |
|---|---|---|
| Double counting | The same pound of nitrate sold to a utility and a food brand inflates impact and destroys trust. | Multiplicative stacking in the model; one ledger entry per unit, one buyer per entry. |
| Over-crediting | Soil carbon and nitrate models can be wrong at field scale, and the error is not random. | Confidence tiers pay only a share of modeled outcomes; a 10% reserve absorbs shortfalls. |
| Reversal | Tillage can release stored carbon; a practice can simply stop. | Pay-as-you-go: the dividend stops when the outcome stops, so no one prepays for permanence. |
| Who gets paid | About 39% of US farmland is rented, and most landlords do not farm. | The dividend follows the acre; the split between owner and operator is written into the lease. |
| Buyer commitment | Prices for nitrate and carbon are thin and volatile; a dividend that swings wildly is not a dividend. | Multi-year price commitments per unit, with public programmes as anchor buyers. |
| Model risk (ours) | The adoption curve is fitted to three points; Maryland may not generalise; prices are scenarios. | Every assumption is published and tagged; a pilot exists to test exactly these numbers. |
11What we are building toward
Measurement first. Then a pilot. Then the ledger.
The Ecosystem Dividend is a direction for TerraValue, not a product we sell today. Every step toward it starts with the same thing: outcomes measured well enough that someone will pay for them.
- Now: measure the outcomes. The field model already resolves a pin to the USDA soil survey and thirty years of climate, and runs a soil-water balance, a nitrogen budget, attainable yield and the economics for that field against a conventional twin. Next: calibrate the nitrogen budget against NRD monitoring wells and add the field-to-well layer.
- Next: pilot one watershed. One water utility or natural resources district, one supply-shed buyer, a cohort of farms, in a Nebraska valley where towns are already paying for nitrate. Pay on modeled outcomes, measure wells and soil alongside, and test whether the confidence ladder holds.
- Later: build the ledger. A registry that sells each outcome once to the buyer who values it most, and pays stewards one annual dividend per acre.
12Limitations
- The logistic fit uses three census points for three parameters; it matches them exactly and cannot test itself.
- Maryland’s adoption also reflects Chesapeake Bay regulation and a long winter; it may overstate the payment response elsewhere.
- The national projection assumes buyers exist at scenario prices. It sizes the pool that would be needed; it does not prove demand.
- Cover-crop adoption stands in for the whole bundle, because it is the only practice with a clean census time series.
- The value-gap bar uses societal benefit-transfer values, not model outputs. Its carbon slice is priced at $51/t, the 2021 interagency interim value the federal government withdrew in 2025. The dividend uses a separate set of price references and outlook assumptions.
- The resilience line is priced at today’s cover-crop insurance discount, which pays for enrolled acres. It is a practice payment, not yet a verified resilience outcome.
- Outcomes in sections 4 and 6 to 8 are field-average estimates for tile-drained corn–soybean in the Corn Belt; other systems will differ.
- The Nebraska figures in section 5 are outputs of a separate field model whose equations and parameters are not published here; its validation status is in the working paper.
Model outputs are estimates, not guarantees or offers of payment. The dividend model and its tests live alongside the site code, and every chart in this paper is computed from it or from the field model’s published outputs.
AMethods and assumptions
Every assumption, tagged.
DATA a published figure · DERIVED arithmetic on published figures · DESIGN a parameter of the proposed mechanism, which a pilot would test.
Table A1. Practices, per acre per year, mid value and range.
| Practice | Carbon, t CO₂e | Nitrate cut | Cost − savings | Yield drag | Sources |
|---|---|---|---|---|---|
| Cover cropsA winter cereal rye cover between cash crops. | 0.47 (0.36–0.59) | 31% (15%–45%) | $37 | 2.25% | Poeplau & Don 2015 · Iowa Nutrient Reduction Strategy · SARE, cover crop cost baseline · Deines et al. 2023 |
| No-tillPlant directly into last season’s residue; no tillage passes. | 0.16 (0.00–0.31) | 0% (0%–5%) | −$15 | 5% → 3% → 1% → 0% | Powlson et al. 2014 · Pittelkow et al. 2015 |
| Nitrogen right-sizingTrim N to the economic optimum rate (about 15% less) with split timing. | 0.05 (0.03–0.08) | 10% (5%–15%) | −$11 | 0% | IPCC 2019 Refinement, Vol. 4 Ch. 11 · Iowa Nutrient Reduction Strategy |
| Prairie stripsConvert ~10% of the field to native prairie in contour strips. | 0.10 (0.05–0.16) | 10% (5%–20%) | $30 | 0% | Schulte et al. 2017 (PNAS) · STRIPS economics · Gebhart et al. 1994 |
Baseline: Tile-drained corn–soybean field, US Corn Belt; 25 lb nitrate-N lost per acre per year (15–36); gross crop revenue $546/acre. Yield drag is a share of that revenue by year; the last value persists.
Table A2. Price scenarios. Carbon: 2024 land-use credit average; BloombergNEF 2030 high-quality and removals-only outlooks. Nitrate: PENNVEST auction, Virginia trading, Maryland Conowingo fee. Habitat: CRP averages per acre of habitat. Resilience: Iowa and Illinois premium discount.
| Scenario | Carbon $/t | Nitrate $/lb N | Habitat $/ac | Resilience $/ac |
|---|---|---|---|---|
| ConservativeToday’s thin markets, frozen in place. | $10 | $2.50 | $72 | $0 |
| BaseReference program prices with a carbon-price outlook assumption. | $20 | $5.00 | $145 | $5 |
| AmbitiousRemoval-grade carbon; utilities pay at their marginal cost. | $20 → $146 by 2030 | $13.00 | $191 | $10 |
Table A3. Mechanism parameters and national anchors.
| Confidence factor κ | 60% / 80% / 95% | DESIGN |
|---|---|---|
| Risk reserve r | 10% | DESIGN |
| MRV & admin fee f | 10% | DESIGN |
| Early-adopter carbon rate | 50% | DESIGN |
| Carbon-only farmer share | 60% | DATA |
| Cost-share contract | 3 years | DESIGN |
| US cropland, 2022 | 382M acres | DATA |
| Cover crops, 2012 / 2017 / 2022 | 10.3M / 15.4M / 18M | DATA |
| Logistic ceiling · rate | 19.35M · 0.246/yr | DERIVED |
| Maryland anchor | $50/ac → 27.3% | DATA |
| Technical potential | 60% | DESIGN |
References
- BloombergNEF carbon credit outlook, 2024
- CBD case study
- Central Iowa Water Works
- City of Bayard notice
- Congressional Research Service
- Deines et al. 2023
- Ecosystem Marketplace, 2025
- EPA, Virginia nutrient trading case study
- European Commission
- farmdoc daily, 2023
- Flatwater Free Press on treatment costs
- Gebhart et al. 1994
- IIED, Perrot-Maître 2006
- Iowa Dept. of Agriculture
- Iowa Nutrient Reduction Strategy
- IPCC 2019 Refinement, Vol. 4 Ch. 11
- Maryland Dept. of Agriculture
- National Academies, 2020
- North Platte NRD
- Open-Meteo historical weather API (ERA5 reanalysis)
- PENNVEST nutrient credit auction
- Pittelkow et al. 2015
- Poeplau & Don 2015
- Powlson et al. 2014
- Rural Radio KOLT, Sept 2026
- SARE, cover crop cost baseline
- Schulte et al. 2017 (PNAS)
- STRIPS economics
- UNL CropWatch on the Nitrogen Reduction Incentive Act
- USDA ERS, cover crop acres chart
- USDA ERS, TOTAL survey
- USDA FSA, CRP statistics (Dec 2024)
- USDA NASS, 2022 Census of Agriculture
- USDA NRCS Soil Data Access (SSURGO)
Cite this paper
TerraValue (2026). The Ecosystem Dividend. TerraValue Working Paper 01, revised 22 October 2026. terravalue.tech/perspectives/ecosystem-dividend
Respond to this paper
Tell us where it breaks.
We are looking for a watershed to pilot in, buyers who would commit a per-unit price, and people who think an assumption above is wrong. All three help.
← All perspectives